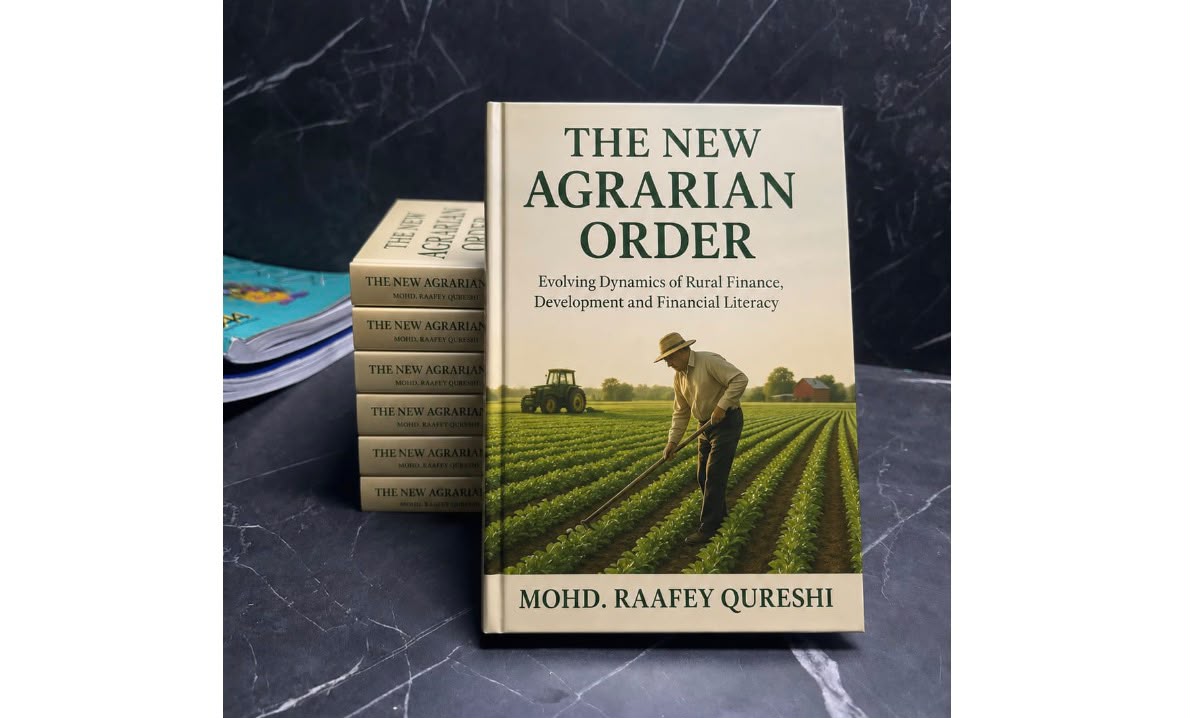
I am Mohd Raafey Qureshi, author of The New Agrarian Order, a book exploring the intersections of rural finance, agricultural development and financial literacy that has sold more than 250 copies. Through its policy analysis, the book examines how financial institutions, development programmes and practical financial knowledge can work together to improve rural livelihoods. Drawing on these themes, I propose five policy recommendations that could help India make its rural financial ecosystem more accessible, responsive and useful to farming households.
1. Promote ‘Harvest Indexed Liquidity Corridors’
Farmers do not receive salaries monthly. They have large upfront costs incurred at planting time and will only receive money all at once four/five months later when they sell their crop at mandi. However, most loan products follow a 30 day urban repayment cycle. Meaning that when repayment dates occur mid-crop season, even the most profitable farmer is left in a difficult situation.
We should promote guidelines for banks to provide Harvest Indexed Liquidity Corridors. By supporting RRBs and cooperative banks to index their loans to regional kharif and rabi seasons, this ensures repayments will happen when the farmer will have cash on hand. This can be made comfortable for local branches by encouraging apex institutions to provide liquidity windows seasonally. Everyone benefits - the farmer has extra breathing space and the bank receives better repayment rates.
2. Promote ‘Digital Agrarian Footprint’ as Collateral
Historically, formal lending has required clear land titles and tax details. Whilst this works well in urban areas, it inadvertently excludes many tenant farmers, sharecroppers, and rural retailers who work hard everyday.
Policies can help to close this gap. By promoting banks to recognise the value of having a Digital Agrarian Footprint. Tenant farmers now have numerous data points to prove their farming activities. UPI payments, Electricity bills, Seed purchases from the local cooperative and FPO delivery notes. We encourage regulators and lenders to adopt models that utilise this real-world data alongside satellite crop data. This helps the bank to lend to the farmer based on their proven work ethic and cashflow.
3. Promote Blended Finance for ‘Micro Storage Credit Links’
Every harvest season we see a common issue. Smallholders require extra cash quickly to pay for inputs and domestic costs. Therefore, many will sell their crop the very week they harvest.
Whilst electronic negotiable warehouse receipts (e-NWR) were created to help, they work well for those close to major trade hubs. For the farmer with two acres in a remote block of land, transporting forty bags of grain to an accredited warehouse far away often simply won’t make economic sense. We would love to see policies for blended finance to help with micro-storage. With government schemes providing a small first loss cover, the commercial banks feel confident lending to FPOs to create small local cold rooms and godowns. These local godowns can be connected directly to their banking apps so the farmer can store their crop just two km from their home. They can then take a short working capital loan using their phone against this stored crop and wait six weeks for the mandi prices to rise.
4. Build ‘Dual Mandate’ Agriculture Extension
During our research for The New Agrarian Order one thing that appeared was that financial literacy can’t be taught in isolation. Every decision made on the ground regarding agronomy, whether trying new drip irrigation, changing feed mixes or purchasing weather insurance, there is always a financial aspect.
We would love to see collaboration between agricultural and banking ministries to create a Dual Mandate Extension Framework. We have an incredible network in our Krishi Vigyan Kendras, PACS secretaries and FPO staff. When an extension officer visits a farmer to show them how a new seed variety works, we should support them and train them to explain the basics of the maths involved. How much working capital will they need, how will the interest build and how crop insurance protects them. Simple voice tools can be added to their mobile app to provide older or new users with confidence to use these services easily.
5. Provide ‘SHG to Enterprise’ Graduation
Very few programmes in the world have created the same level of trust as India’s Women’s Self Help Groups (SHGs). Decade after decade they have proved that micro-saving and micro-credit within peer groups can create huge changes in household nutrition, education and repayment.
We would love to see a framework in place to help SHGs graduate. Many SHGs have matured and are looking to move beyond micro-consumer loans and create small businesses in the village. We encourage policies that provide slightly increased working capital lines alongside basic digital accounting and direct buyers. This provides women-led groups with a reliable progression to become local job creators.
Future Outlook
The exciting thing about the current state of policy in India is that none of these steps require any new institutions to be created. The banks, cooperatives, SHGs and digital infrastructure are already in place in the districts. By simply gently aligning credit lines, local storage and financial knowledge to the life of a household in the village, we can help create sustainable prosperity for rural India.
Book Link:
https://www.amazon.in/New-Agrarian-Order-Development-Financial/dp/B0FZMXHS2P